How long heirs have once a reverse mortgage comes due
The hard part of a reverse mortgage is almost never the arithmetic. It is the calendar. Servicers set deadlines once the loan comes due, they can grant extensions, and nobody should assume an extension is automatic.
So before anything else, get the reverse mortgage servicer on paper. Ask for the payoff demand, the deadline, and the documents they want from the estate. Families who do that in the first week tend to keep their options. Families who wait tend to lose them.
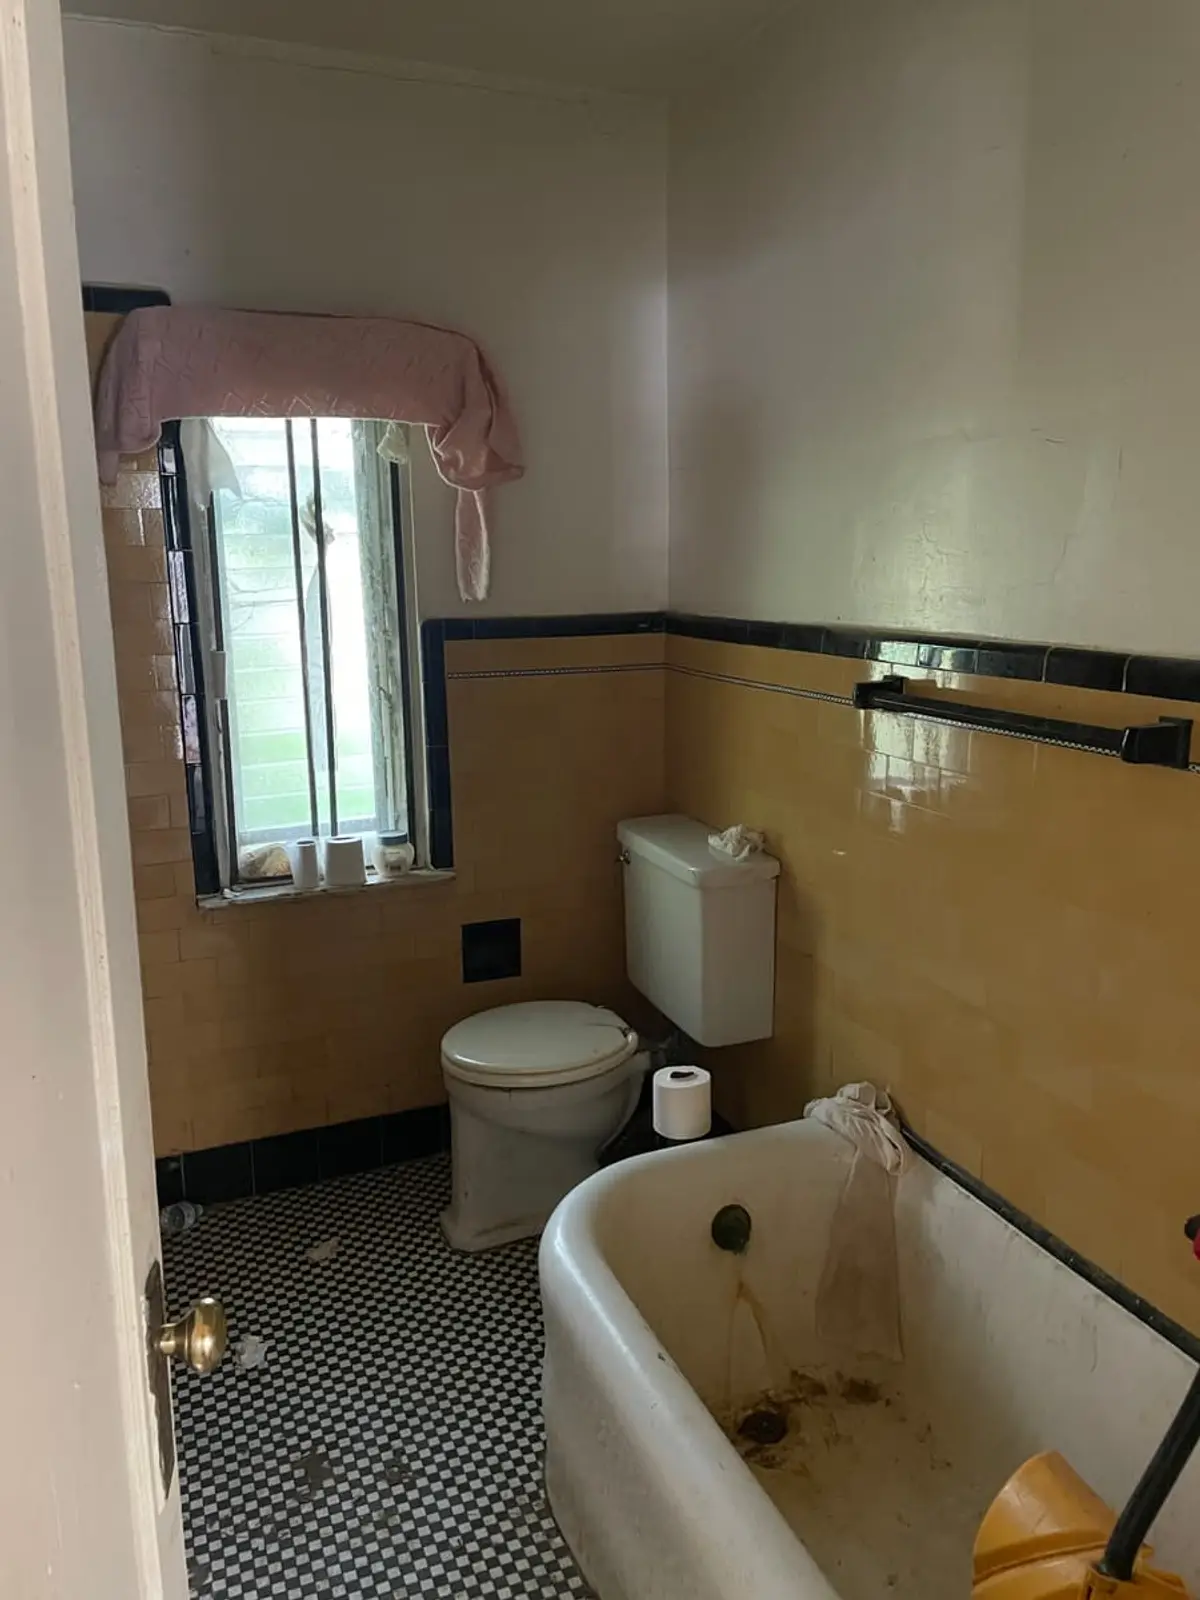
What the heirs actually owe on a reverse mortgage
Here is the distinction that decides everything. On many of these loans the heirs owe the lesser of the reverse mortgage balance or a set share of the appraised value, and on federally insured loans there are protections for heirs when the balance has grown past what the house is worth.
We are not going to state your loan's terms as settled fact, because reverse mortgage documents differ. Have an attorney read yours. The gap between those two figures often decides whether selling leaves anything for the family.
The Hempstead market underneath this
The median is up 6.02% year over year as of 2026-05. A firming market gives you a little room for error on price, which is worth more than it sounds when the house is not in showable condition. At a $660,000 median, Hempstead is a market where buyers expect to do some work. That helps a seller with a dated house and hurts one with a genuinely broken one, because the pool that will take on a project is not the same pool that will take on a gut. Houses here take a median of 57 days to go from listed to under contract, and that clock only starts once the property is ready to show.
A six-bedroom on Princeton Street. A five-bedroom on Flint Avenue. A three-bedroom on Carolina Avenue. All of them in Hempstead, all bought by us.
What we bring, beyond the money
Reverse mortgage estates are where an inexperienced buyer does real damage. A financed buyer who collapses at week six of a deadline like this can cost a family the house outright.
We buy with our own funds, we have worked these payoffs in Nassau County, and we know how the servicers behave. We will support an extension request with a signed contract, coordinate with your attorney, and tell you plainly if the numbers mean the heirs are better off handing the keys back instead.
Why a cash sale suits a reverse mortgage deadline
The constraint on a reverse mortgage is a date set by somebody else, and that is exactly where a sale which cannot fall through is worth more than a slightly higher one that might. The median house in Hempstead sold for $660,000 and took about 57 days to go under contract, then another 45 to 60 days waiting on the buyer's mortgage. That is 102 to 117 days in total, for a house that was ready to show on day one.
Against a reverse mortgage deadline, that second wait is the one that hurts. We have no lender, so there is nothing on our side to appraise, underwrite, or change its mind in week five.
What the two paths cost in Hempstead
These are the two routes open to you with a house with a reverse mortgage, priced against what Hempstead houses actually sell for.
Work it against Hempstead's own numbers. The median sale here is $660,000. A 5% commission on that is $33,000, and seller closing costs of about 2% add roughly $13,200. Those are costs we can cover on our side. That is $46,200 gone before anyone counts the repairs it took to get the house listable.
There are two waits in a listed sale and people usually only count the first. In Hempstead the median house takes about 57 days to go from listed to a signed contract. Then it waits again, typically 45 to 60 days, while the buyer's lender orders an appraisal and underwrites the loan. Call it 102 to 117 days from sign to keys, assuming nothing goes wrong.
The part worth understanding is what a signed contract actually guarantees, which is less than most sellers assume. A retail buyer with a mortgage contingency can walk away right up to the end. If they do not qualify, if the appraisal comes in under the price, if they change their mind and let the financing lapse. A share of deals die exactly there, after months of waiting, and the house goes back on the market with time on it. We are not borrowing anything, so there is no lender to satisfy, no appraisal to come in low and no contingency to exercise.
| Listing with an agent | Selling to us | |
|---|---|---|
| Sale price | $660,000 (Hempstead median) | Our written offer |
| Commission | −$33,000 | None |
| Seller closing costs | −$13,200 | We can cover them |
| Repairs before listing | Out of pocket | None |
| Cleanout | Yours | Ours |
| Showings | Until it sells | One visit |
| Listed to signed contract | 57 days (Hempstead median, once listable) | 24 hours to a written offer |
| Contract to closing | 45 to 60 days (waiting on the buyer's lender) | A date you choose |
| Total wait | 102 to 117 days if nothing falls through | Yours to set |
| Can the buyer walk? | Yes (mortgage contingency runs to the end) | No financing to fall through |
| Before repairs and carrying | $613,800 | The number we put in writing |
The agent column uses a 5% commission and about 2% of seller closing costs, which are typical rather than fixed. It leaves out repairs and holding costs because no two houses are alike there. Where a house is in good condition, listing with a capable agent can beat our number, and we will be upfront if that is the case.
A reverse mortgage also comes due when the borrower moves out
The rule that catches people is the one about occupancy. A reverse mortgage generally requires the borrower to live in the home, so a permanent move into care can trigger the payoff just as surely as a death does.
Unlike a death, nobody sends the family a letter about it right away. If your parent has moved out and their reverse mortgage is still on the house, treat the clock as already running and confirm the specifics with the servicer rather than with anybody else.
How selling a house with a reverse mortgage in Hempstead works
- 1
You tell us about the house
An address in 11550 and a rough idea of condition. Two minutes on the phone or the form. We do not need photographs, a clean house, or anything fixed first.
- 2
One short visit
One of us comes by once, usually for less than half an hour. On a colonial or cape cod like most of Hempstead, what we look at closely is the roof, the boiler and the wiring, not the finishes.
- 3
You get a number in writing
Within 24 hours, as a written figure rather than a range or a "starting around". Take it to a Nassau County agent for a second opinion if you want to. On a house already in showable condition, listing may well beat us, and we would rather you knew that.
- 4
The date is up to you
Close quickly, or set a date months ahead to fit probate, a tenant or your own move. Either way there is no 102 to 117 days of a Hempstead listing looking for a buyer and waiting on a mortgage approval.
Repay, refinance, sell, or hand it back
Heirs sometimes decide a reverse mortgage has swallowed the house and there is nothing left to save. Sometimes that is correct, and a deed in lieu is a reasonable end to it.
Check first, though. We have seen families walk away from real equity because the reverse mortgage balance looked larger than it was, or because nobody compared it against what the Hempstead house would actually sell for. Get the payoff, get a written offer, then decide. Both are free and both take days.
Common questions
The borrower has died. How long do we have to sell the Hempstead house?
The servicer sets that deadline, so the answer has to come from them in writing. What we can tell you from Nassau County experience is that the first two weeks matter more than any of the ones after, so make the call today rather than next month.
What if the reverse mortgage balance is more than the house is worth?
On a federally insured loan there are protections for heirs in exactly that situation. It is a question for an attorney who can read your specific reverse mortgage documents, because the answer turns on the loan rather than on the general rule.
Can we get an extension on the reverse mortgage deadline?
Servicers have discretion to extend and they do use it, particularly when the estate can show a signed contract and a real closing date. Nobody can promise you one, so ask early and put the request in writing.
Mom moved into a nursing home. Is her reverse mortgage due now?
Occupancy is usually a condition of the loan, so a permanent move out of the Hempstead house can make it due. Ask the servicer and ask an attorney. In the meantime the house is still accruing taxes, insurance and interest.
Does the servicer have to approve the sale?
Not in the way people expect. A sale that satisfies the reverse mortgage payoff closes like any other. It is only when the proceeds fall short of the balance that the servicer's agreement becomes part of the conversation, and your attorney should lead that.